#On the Account
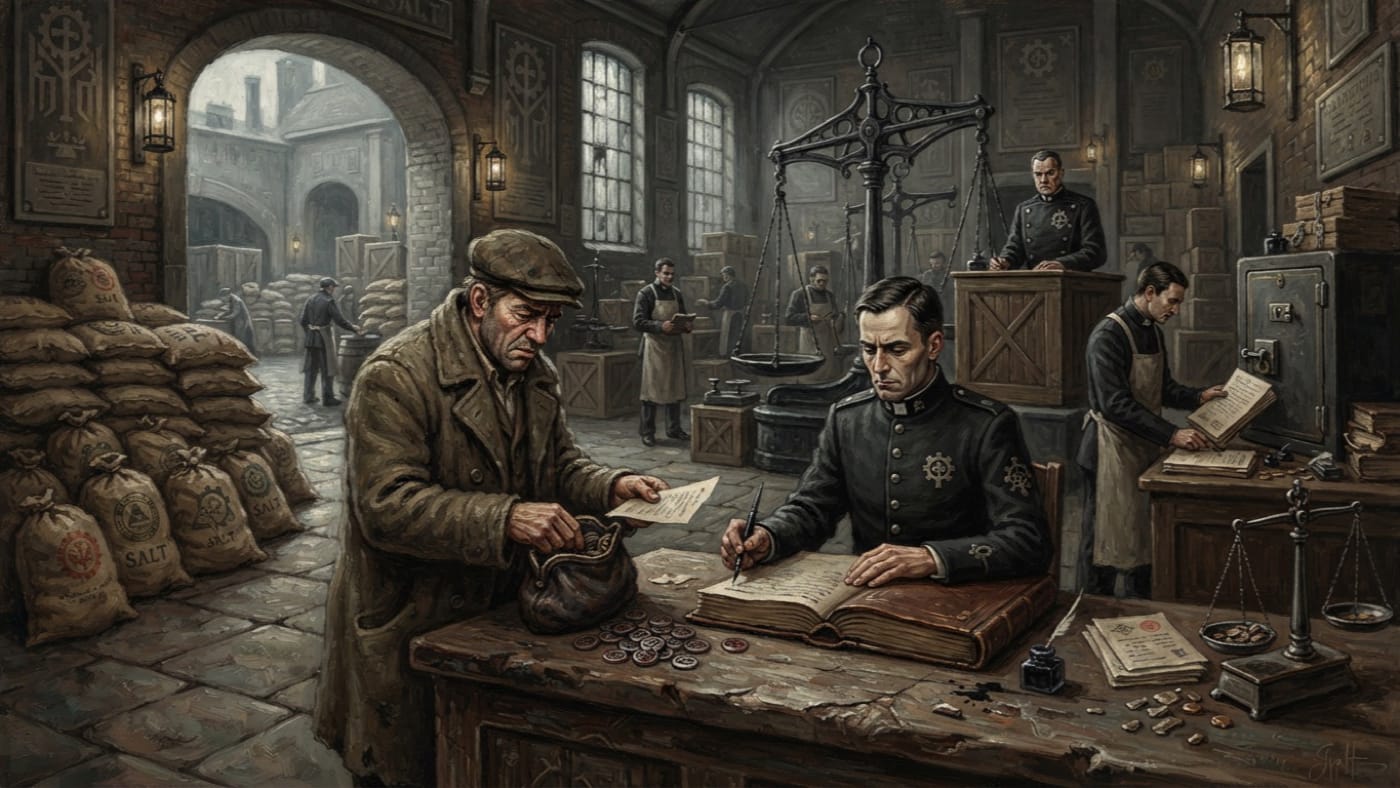
A salt factor stands in a harbour weigh-chapel with a purse of iron Crowns and forty sacks on the quay behind him. He thinks he has come to pay. He has come to be converted, in stages and under seal, from a man with salt into an entry with a balance. He may have his salt back when the entry closes.
Harbour clerks, Tithes correspondence and my own entry on the Meta-Levy all call this conversion "Crown of Grace accounting." Nobody chartered it. I have looked for a founding instrument, a council sitting or a treatise of reckoning under that name, and found only usage, which in the Church is the older and more durable kind of law. The phrase covers a sequence of documented practices: recognised value, true measure, assessment, receipt, reconciliation and remittance. Each practice has its own office and its own grudges. Together they make a cargo legible to Strasbourg.
Four things must be kept apart, and merchants never manage it. The coin is iron. The obligation is ink. The payment is an act. The proof is a seal. A man may hold the first and discharge the third and still be refused his salt for want of the fourth.
#On Recognised Value
The Crown of Grace is stamped iron, marked with the Synod's sigil and consecrated at the mint by priestly blessing. A smith would price it by the pound and be wrong. Its value rests on the Synod's recognition, which is a harder metal than any assayer has yet put under acid. The iron issue was regularised in A.S. 92, two years after the Concordat. The accounting built on it has no birthday of its own, and I decline to invent one. The theology of the coin belongs to Coinage Orthodoxy, and I will not repeat it here beyond the two clauses every harbour clerk knows by heart. Ledgers are holy documents. To cheat in coin is blasphemy, punishable as heresy.
The second clause gives the accounting its teeth. The first gives it its liturgy. A harbour ledger is kept with the reverence owed a register of baptisms, and with much the same expectation that it will be produced on the Last Day.
The Crown is the unit of account. It is seldom the whole of the payment. Authenticated relics hold value in their own right, goods change hands by sealed weight, and licensed tokens pass wherever their licence permits. The mixed ports settle partly in foreign tender and on credit, a habit the plural entry on Crowns of Grace records with visible distaste. An obligation written as forty Crowns states what is owed. It says nothing about how many iron discs crossed the table.
Under Crown of Grace accounting, every harbour obligation is paid in Crowns of Grace.
Corrected before sealing. Every harbour obligation is stated in Crowns of Grace. It may be settled in coin, authenticated relic, sealed goods, licensed token, foreign tender or credit. This entry gives no conversion schedule between them, because the Bureau has given none to me.
#On Harbour Reckoning
Cargo comes ashore as a rumour and leaves as a document. The first stretch of that passage belongs to the weighers of the Bureau of Commerce, licensed clerks whom the quay calls Grain Judges, among less printable names.
The clerk checks the manifest against the cargo and the bearer against his papers. Then he calibrates the scale before witnesses. Synod scales are set against reliquary fragments, slivers of bone and pinches of saint-ash. A clerk who calibrates alone leaves the auditors to decide later whose side his scale was on. "Never calibrate alone," the weighers say, and they keep that rule more faithfully than most of the Creed.
The goods are weighed twice, gross and then net. Sacking, barrel staves and the factor's thumb on the pan come off by subtraction or by force. The clerk computes the tariff at whatever rate war, season and sector discipline have set that month. He applies a purity mark or writes a confiscation slip, seals a clearance and issues a ticket. A copy goes to the archive for the auditors. The weighers' maxim for the double weighing is "two-pass or riot," and the quay has tested both halves of it.
Now the Bureau of Tithes arrives, or reveals that it has been standing there all along with its scales, ledgers, seals and escort. A Tithe Assessor demands the due and takes it in coin, salt, goods or tokens. In return he issues a sealed receipt or an arrears mark. Where the weigher's ticket ends and the assessor's receipt begins varies from harbour to harbour. I have read three jurisdictional memoranda on the question, and they agree only that the other Bureau started it. Commerce measures the cargo, and Tithes collects on the measurement. Both keep a copy, and both copies are holy.
#On the Cost of Collection
The harbour due is assessed. The factor reaches for his purse. He is early.
Between primary assessment and acceptance of payment, the Meta-Levy attaches. A payment taken before that point would leave the obligation, in the Bureau's phrase, fiscally naked. The instrument began as a temporary supplement proposed on the Upper Moselle circuit in A.S. 117. The Palatine Counting House standardised it in A.S. 127, and it survived the Assembly of Thrones challenge of A.S. 138. The early schedule set harbour dues at one-thirtieth. Grain bore one-fortieth. Harbour dues still carry an additional transit verification fraction. A cargo that has crossed water must be verified as having arrived, verification is labour, and labour is billable.
Recording the levy is labour too. Receipt, registration, vault transfer and confirmation each carry a sub-charge. Public doctrine holds that the sub-charge bears no Meta-Levy of its own. Inside the Bureau, the sub-charge is called "self-sustaining." I set these two statements side by side in the ledger and leave them to glare at each other. Reconciling them is outside my office, and the Bureau of Tithes has given no sign that it wants them reconciled.
No schedule open to me gives the current harbour rate. I will not build one from the parent entry's village arithmetic, which concerns a parish and its grain. The factor learns his rate the way every subject does: at the table, from the clerk, after the queue.
#On Proof and Discrepancy
The receipt releases the salt. The receipt needs a seal, and the seal needs three things to agree that are rarely in the same room: what the clerk wrote, what the assessor received and what the strongbox holds. Each evening the weigh-chapel shuts, the copies are laid edge to edge, and the clerks try to make them agree. That is reconciliation.
Any disagreement holds the cargo. A disputed seal on a manifest will do it. So will a net weight that two ledgers record differently, or a receipt blank numbered for another week. Any of these keeps the factor's sacks on the quay while his full purse sits beside them, the money present and the payment incomplete. The salt will keep. His buyer may not.
Assessor audits count blank receipts and test seal wear against dates of use. They compare receipts with collected stores and comb household rolls and exemptions for patterns. Commerce audits check seals first, then calibration witnesses, then the ledgers against market prices. Anything that fails to match, the weighers say, becomes a person. The frauds are dull and permanent: the bribe offered as a donation, the lighter weight set kept for friends, the forged seal, the coins sewn into a sack seam. Worst is the double ledger, which keeps the honest figures privately and shows the Creator the clean ones.
Remittance carries the reconciled sums to the Palatine Counting House, and at scale the controls multiply. The Crowns of Grace entry prescribes red-black ink for high totals and double cords on bags above a hundred Crowns. Chests above five thousand get a closing chime test, and sums above fifty thousand need additional documentation. The same entry puts the yield of Marseille's Salt Dues near 1.4 million Crowns a year. I report these figures as that entry gives them. I have not totalled the harbours myself, and I will not.
#On Present Application
As of A.S. 201, Crown of Grace accounting governs the harbours that keep their books under Synod tithe law. Ports outside that law keep their own iron and decline our auditors. The British decline with great courtesy. Archbishop Salome Veyrault, Archbishop of Tithes since A.S. 189, administers the system from the Palatine Counting House. She did not invent the Meta-Levy or the weigh-chapel. She has made both punctual.
The Bureau of Records keeps the archive copies. The Bureau of Doctrine, which employs me, certifies that the ledgers are holy and the sums correct, and the first certification is the more confident.
The factor's sacks remain on the quay, awaiting a second seal.